In August 2026, while transpacific freight rates are hitting new highs, the Far East–Europe route is tracing a distinctly different curve. SCFI European route rates have fallen for consecutive weeks, spot transaction prices are gradually drifting toward $4,000/FEU, and the subtle tug-of-war between carriers' "announced increases" and "actual decreases" is intensifying. This is not a cliff-edge collapse but a supply-and-demand-driven gradual decline — the convergence of three forces (peak season dividend exhaustion, concentrated new vessel deliveries, and Suez Canal resumption expectations) is pushing European route rates into a gradual decline channel.
The latest SCFI data from August 7 showed the Far East–Europe route at 2,964/TEU, down 75 or 2.46% week-on-week; the Far East–Mediterranean route at 4,048/TEU, down 141 or 3.36%. Meanwhile, the SCFIS European route settlement index stood at 3,383.88 points, down 135.93 points or 3.9% weekly.
This is not a single-week fluctuation. Looking back at July 31 data, the SCFI European route was already at 3,039/TEU, down 3.68% weekly; the Mediterranean route at 4,189/TEU, down 3.72%. From late July to early August, European route rates have declined for four consecutive weeks, with a cumulative drop exceeding 8%.
The Freightos Baltic Index (FBX) further corroborated this trend: in the first week of August, Asia–North Europe rates were approximately 5,000/FEU, down 14% from the July peak; Asia–Mediterranean at approximately 6,000/FEU, down 16% from the July peak, essentially returning to mid-June levels.
The futures market is also accelerating its pricing of downward expectations. On August 11, the Containerized Freight Index (Europe route) main contract EC2610 closed down 4.55%, with distant month contracts falling 1%–3%. Historically, September contracts from 2023 to 2025 all dropped more than 25% versus August spot rates, with the maximum decline reaching 41.23%. The current September contract discount to August spot is approximately 35%, indicating the market has already fully priced in the end-of-peak-season decline. The October contract valuation range is locked at 1,400–1,850 points, reflecting a consensus expectation of weak demand and capacity oversupply in the second half of the year.
The fundamental pressure on European rate declines comes from continued supply-side loosening.
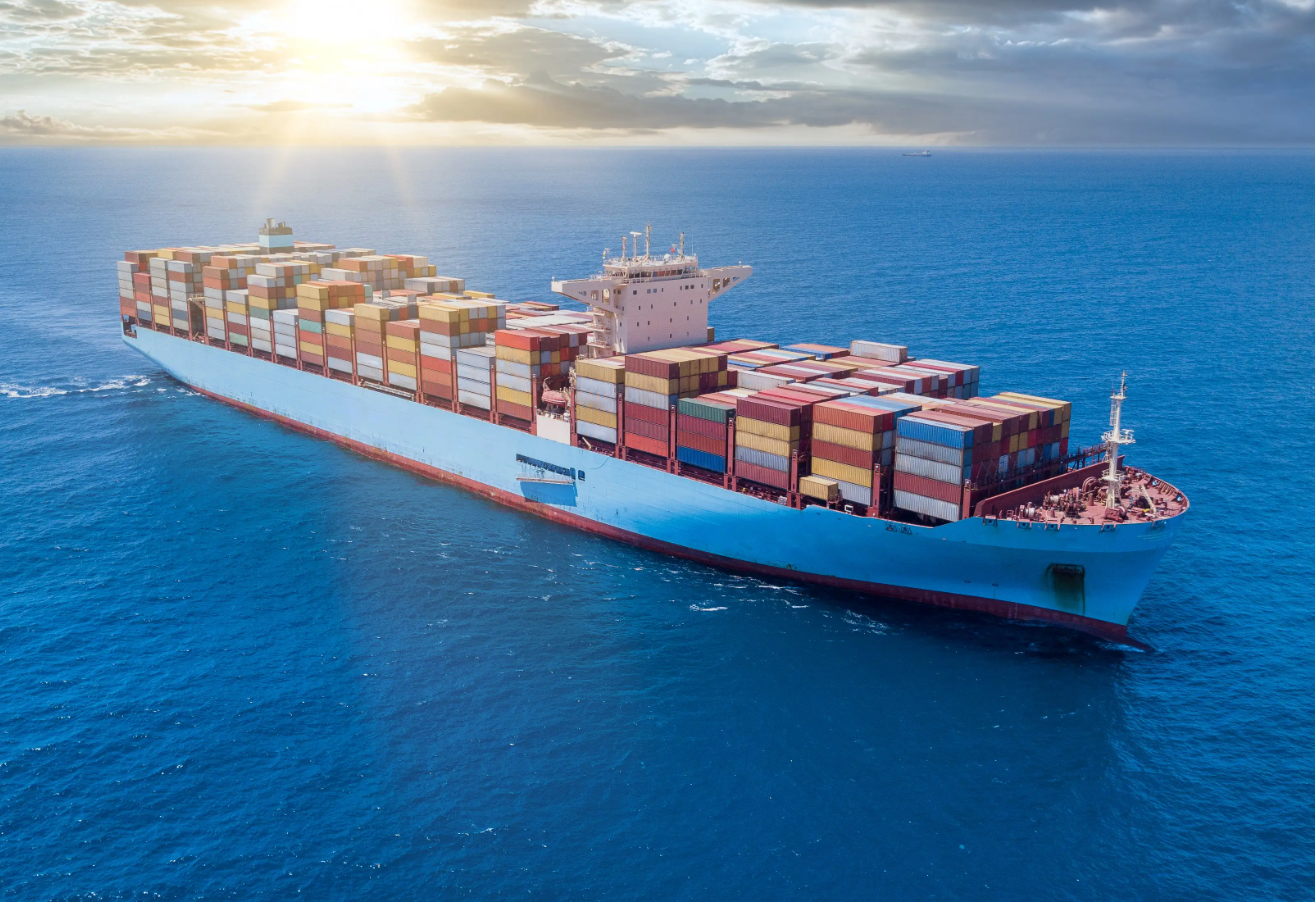
Concentrated new vessel deliveries. Of the approximately 1.477 million TEU of new vessels scheduled for 2026, over 60% will be delivered between June and December, with nearly one-third deployed directly to the Asia–Europe route. Thirteen vessels of 12,000+ TEU have been delivered year-to-date, totaling 237,000 TEU. The nominal capacity growth rate on the Asia–Europe route is approximately 6.4%, while the expected volume growth rate is only 2.5%–3.5%. This gap means significant capacity oversupply in the second half. Weekly deployed capacity on the China–Europe route in August is approximately 308,000–319,000 TEU, rising to approximately 334,000 TEU in September, with supply-side pressure gradually intensifying.
Suez Canal resumption advancing. After the "Majestic Maersk" successfully transited the Red Sea, the Gemini Cooperation (Maersk and Hapag-Lloyd) successively resumed the AE15 Asia–Europe route and the MECL Middle East–US East route via the Suez Canal. On August 10, Maersk announced that yet another Gemini route would resume transit via the Red Sea and Suez Canal. Post-resumption, westbound voyages are shortened by an average of 7 days and eastbound by 14 days, significantly improving vessel turnaround efficiency. If Red Sea routes gradually fully resume, an additional 15%–20% of latent effective capacity would be released.
Hormuz Strait de-escalation signals. Iranian Foreign Minister Araghchi stated on August 11 that Iran and Oman are "very close" to reaching an agreement on the Hormuz Strait transit mechanism. US Treasury Secretary Bessent previously stated that the US might reach an agreement with Iran by August 5 to open the strait. If strait transit resumes, the Middle East geopolitical risk premium previously embedded in freight rates would gradually dissipate, further pressuring European route rates downward.
Carriers are attempting to offset supply loosening through blank sailings. The Ocean Alliance arranged 3 blank sailings plus 3 TBD voyages in August, and the cancellation rate for planned capacity on the world's four major east-west trunk routes reached 10%–14% in the first half of 2026. However, the medium-term supply increment is definitive — capacity control can only slow the decline, not reverse the trend. Overall, current supply is not rigidly tight but rather a question of carriers' "willingness to release," with blank sailing intensity determining the short-term rate floor.
The core assessment on the demand side is "peak season dividend fading, cargo volumes weakening marginally."
Due to the normalization of rerouting, European importers generally started stocking 1–2 months earlier this year, with concentrated June–July shipments having already realized most peak season volumes. By mid-August, European major retailers' holiday stocking was essentially complete. Entering August, booking demand for traditional export categories such as light industry, home goods, and cross-border e-commerce contracted month-on-month, with only new energy vehicles and related components, and mechanical and electrical equipment as long-term deliveries providing rigid cargo floor support.
Macroeconomic data also offers little cause for optimism. The Eurozone July manufacturing PMI final reading came in at 51.9, slightly below the initial estimate and expectation of 52, with growth primarily driven by clearing backlogged orders rather than improved market demand. While the July composite PMI initial reading came in at 50.3, above June's 50.0, marking two consecutive months in expansion territory, the recovery foundation still needs consolidation. Under a high-interest-rate environment, discretionary consumer spending declined, capital expenditure fell, and Eurozone foreign trade import expectations weakened.
Structural differentiation is pronounced: the North Europe main route, with its high proportion of home appliances, machinery, and long-term contracts, maintained relatively stable shipping rhythms with moderate declines; the East and West Mediterranean routes, dominated by cross-border e-commerce and light goods, saw volumes shrink rapidly once peak season passed, with the NCFI East Mediterranean route plunging 8.5% weekly and West Mediterranean 6.1% — far exceeding the Europe route's 2.2% decline. The market broadly expects a 10%–15% volume decline from August to September.
The current European route quotation market exhibits a subtle phenomenon: carriers' "announced increases" and "actual decreases" coexist simultaneously.
Maersk held its Week 33 opening price at 4,600/FEU, refusing to follow the market down, then further reduced its Week 34 quote to 4,400/FEU, a 6.5% weekly decline for large containers. MSC issued an announced increase letter for 7,800/FEU on North Europe 40-foot containers effective August 15, but the actual August price was only 5,704, dropping further to 4,840 in the second half of the month. ONE slashed its price by 1,400 to 4,608, and HMM cut 200. Yang Ming's regular FAK was 4,600, with special pricing reduced to 4,200. OOCL's regular FAK was 5,000–5,100, with volume pricing at 4,900–5,000. CMA CGM's mid-month quote was 3,139/TEU and 5,243/FEU.
Price spreads among top carriers widened to nearly 900. In early August, actual FAK quotes for some sailings had dropped to 4,200–4,300, and according to market research, spot prices may break below 4,000/FEU by end of August. Maersk also reduced its Far East–to–Europe PSS from 500/1,000 to 250/500 effective August 10.
The "announced increase letters" are more of a posture by carriers attempting to guide market expectations, with questionable feasibility amid weakening cargo volumes. Slow spot declines and unfulfilled announced increases — this is the true picture of the current European route quotation market.
The European route's downward trajectory will not be a cliff-edge collapse. First, carrier capacity control remains effective, with blank sailing ratios at elevated levels — the short-term supply contraction effect temporarily outweighs resumption releases. Second, while the Red Sea security situation has eased, uncertainty persists — Maersk emphasized it has contingency plans ready and can immediately resume Cape of Good Hope rerouting if conditions deteriorate. Third, while Hormuz Strait negotiations show positive signals, the parties still differ on core issues such as channel management authority, and no binding document has yet been formed.
However, the medium-to-long-term weakening trend is irreversible. The second-half new vessel delivery peak, the September capacity average increase, and post-peak-season demand contraction — these three forces converging will continue to push European route rate centers downward. For foreign trade enterprises and freight forwarders, the most pragmatic strategy is: monitor the spread between carriers' announced increases and actual quotes, leverage the Premier Alliance's special-sailing windows for favorable pricing; balance long-term contracts with spot market exposure to avoid locking in excessively high rates during a downward cycle; closely watch September capacity deployment data and Red Sea resumption progress, and dynamically adjust shipping rhythms. In a gradual decline channel, flexibility matters more than prediction.
Disclaimer: Data in this article is sourced from public channels for industry analysis purposes only and does not constitute any decision-making advice. Actual freight rates are subject to carriers' official quotations.
Contact: Manager Li
Phone: 021-31056166
Email: sea-giant@sea-giant.com
Add: Room 1708, Pu Chuang Business Building, 1050 East Daming Road, Hongkou District, Shanghai, China
We chat