In late August, the container shipping market is presenting a picture completely different from previous years: at a time when the market would normally be shifting from peak season into the off-season, the Middle East and US East Coast routes are rising against the seasonal trend, with freight rates breaking through key thresholds one after another — 40-foot container quotes on some Middle East routes have crossed USD 10,000, while the SCFI rate on the US East Coast route has surged to USD 9,700/FEU, closing in on the five-figure mark.
According to the National Business Daily, on August 20 the quote on the Shanghai-to-Jeddah route (via Port Klang transshipment) had reached USD 6,500 per TEU and USD 10,200 per FEU. In just about half a month, freight rates on some Middle East routes have climbed from around USD 7,000 to above USD 10,000. Freight forwarders in Qingdao report that rates on most China-origin routes to Middle East transshipment hubs have now exceeded USD 10,000, including destinations such as Kuwait and Iraq's Umm Qasr, while comprehensive transportation costs to inland destinations like Riyadh and Dammam in Saudi Arabia are also at elevated levels.
Shanghai Shipping Exchange data released on August 21 shows the Shanghai-to-Persian Gulf base port rate at USD 5,729/TEU, up 5.7% from the previous week — the strongest gain among all major ocean routes.
The root cause of this surge is a sharp contraction in effective capacity. Tensions in the Middle East persist, transit risks through the Strait of Hormuz have not been eliminated, and the Red Sea and Suez Canal routes remain under geopolitical pressure. Although some vessels have resumed Suez Canal transits, carriers must still weigh navigation safety, insurance costs, fleet deployment and empty container repositioning, making a full restoration of services a distant prospect. The US-Iran memorandum on the Strait of Hormuz has expired without a durable settlement. Although Iran announced an agreement with Oman on a temporary transit plan on August 15 (expected to be available for two to four months), the reassessment of security, insurance and schedule arrangements still takes time, and traffic volumes remain far below pre-conflict levels.
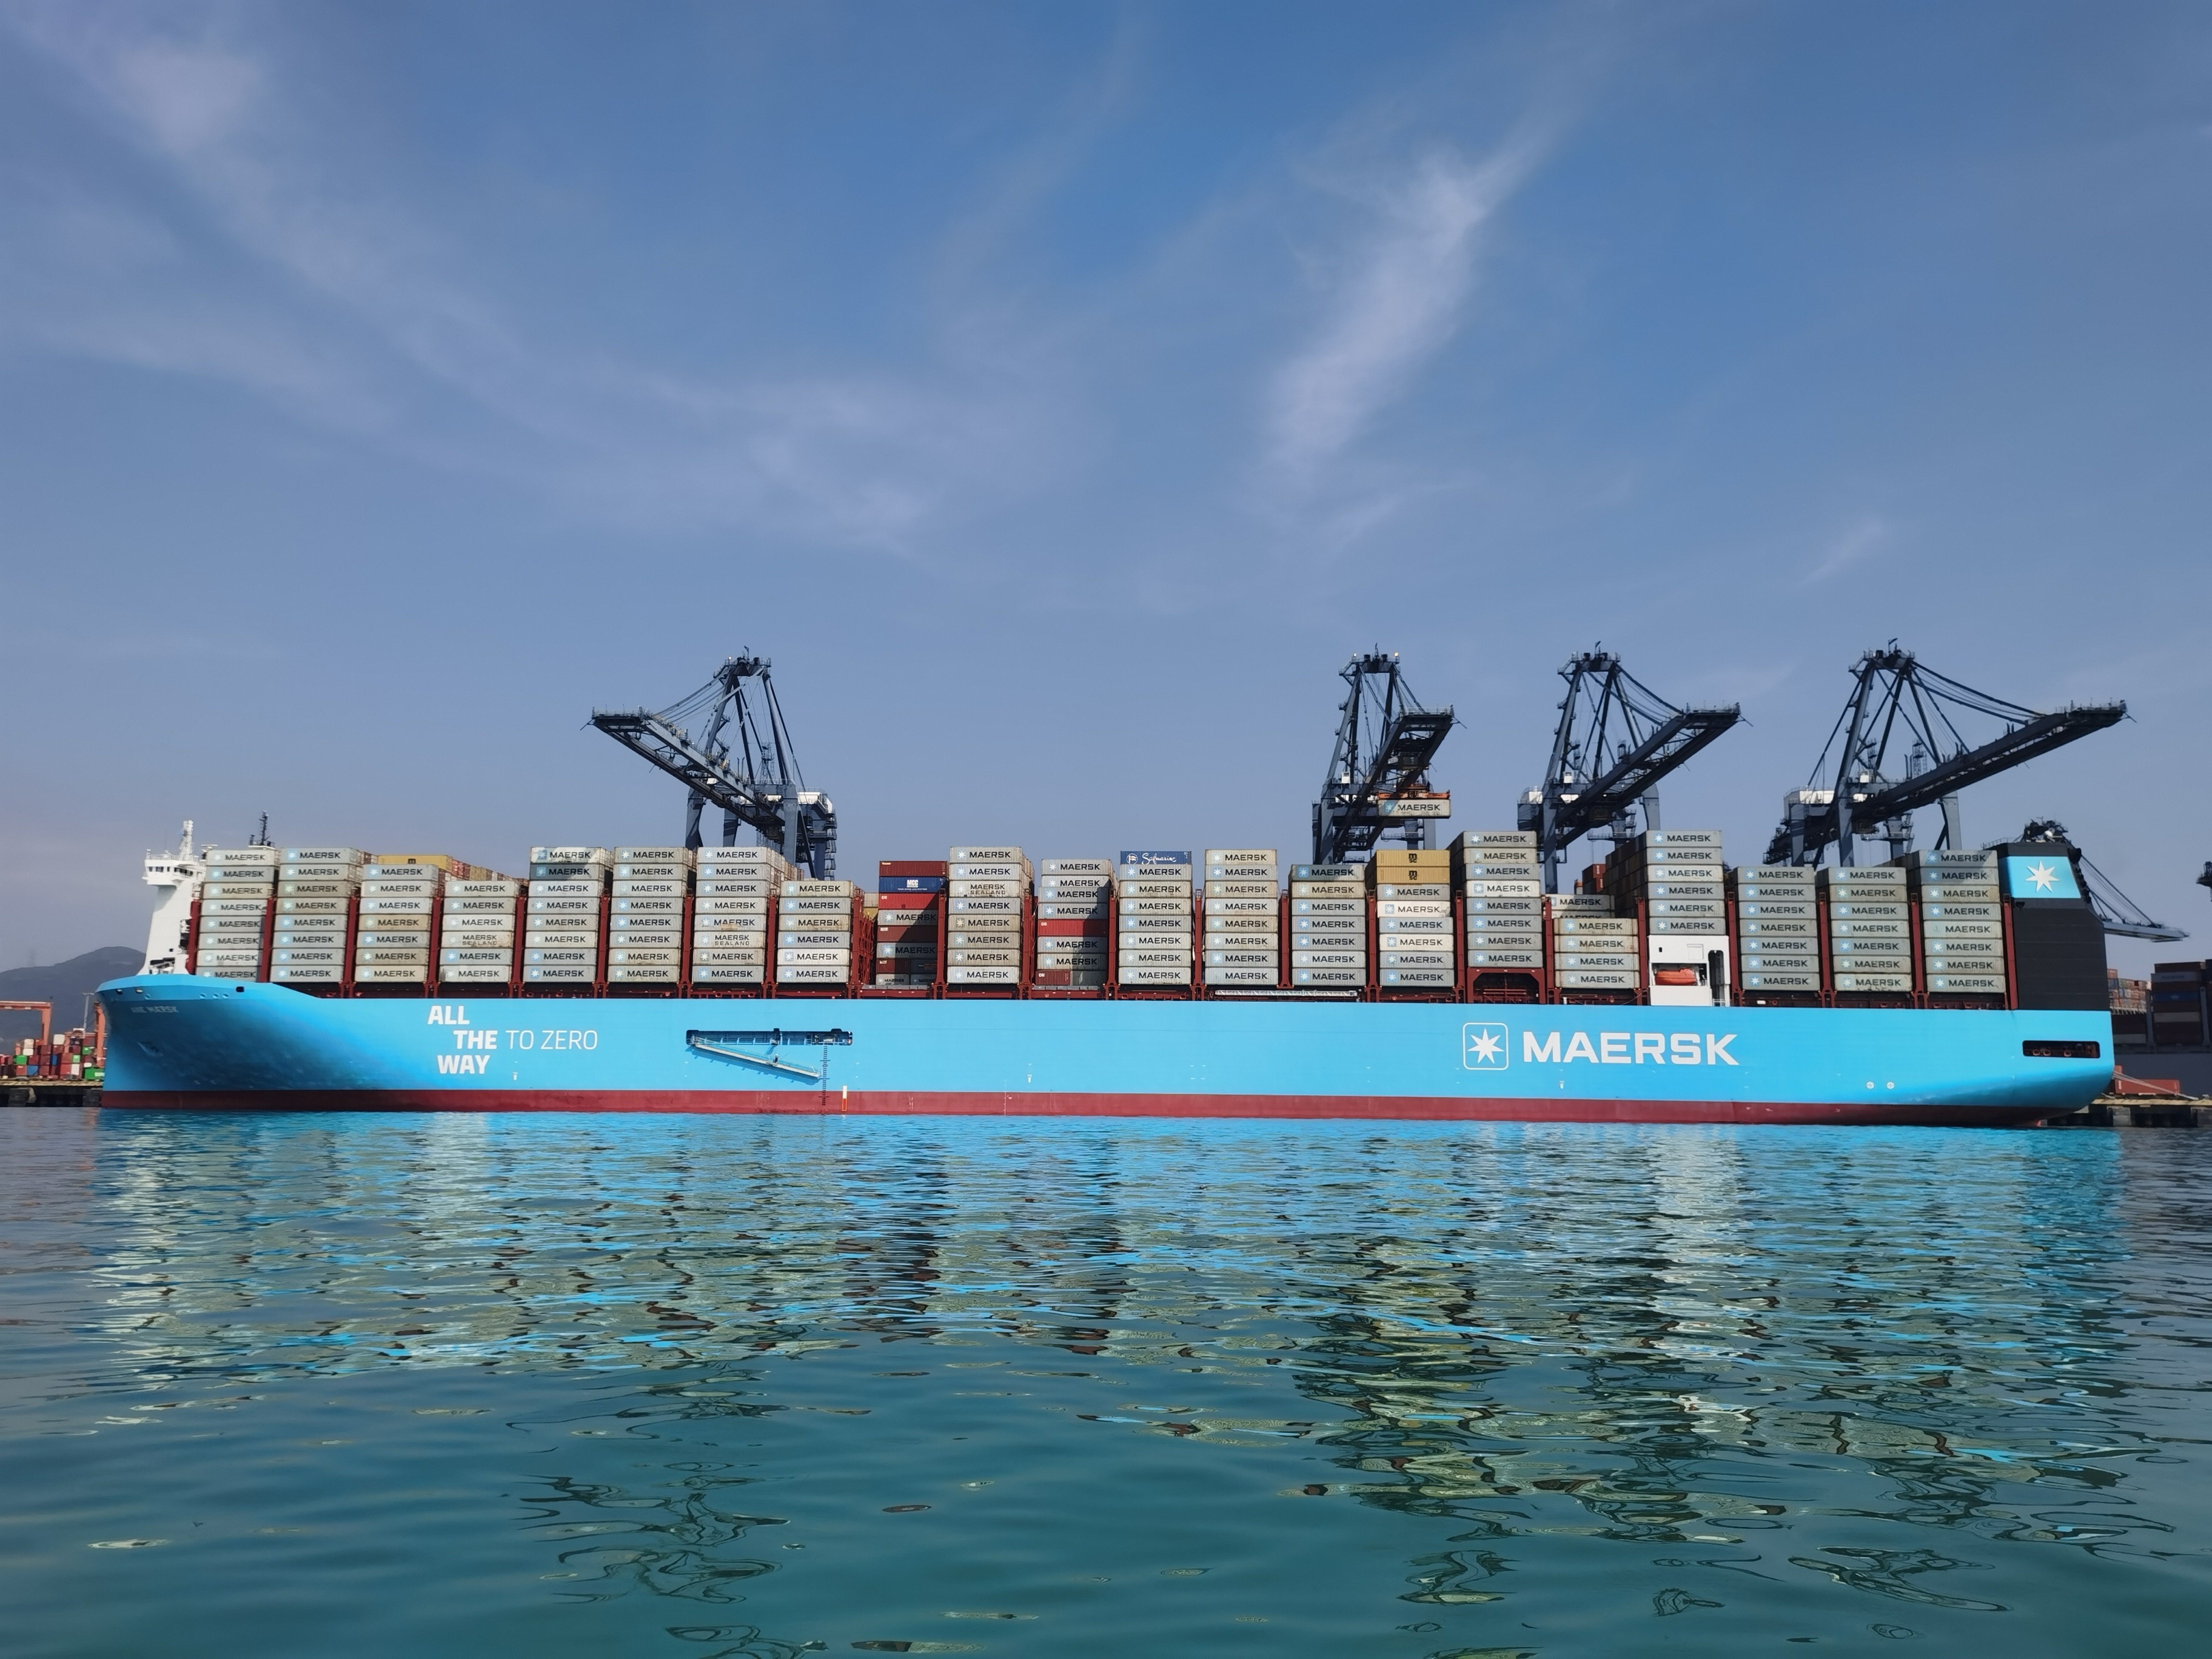
Unlike the Middle East route, which is being pushed up directly by geopolitical conflict, the US East Coast rise stems more from structural supply contraction. On August 21, the Shanghai-to-US East Coast rate rose 1.4% to USD 9,700/FEU, widening the spread with the US West Coast (USD 6,765/FEU) to USD 2,935 — a spread even larger than the total freight cost of the entire US East Coast route before the Middle East crisis erupted on February 28. Peter Sand, Chief Analyst at Xeneta, called it "incredible."
The direct variable driving US East Coast rates higher is Panama Canal restrictions. Due to persistent drought triggered by El Nino, canal water levels continue to fall. The Panama Canal Authority has announced that daily transits will be cut from 36 to 34 vessels starting September 3, and further to 32 from September 15, with some vessels required to transit with reduced loads — capacity losses that cannot be fully compensated by adding sailings. Drewry data shows Asia-to-US East Coast capacity fell about 9% month on month in August, far exceeding the roughly 0.4% decline on the US West Coast, tightening space availability. The latest WCI index shows the Shanghai-to-New York spot rate up 9% to USD 9,507/FEU, and Shanghai-to-Los Angeles up 9% to USD 6,802/FEU.
Carriers are preparing another round of increases. Industry sources say shipping lines are rolling out September 1 reference rates with the US East Coast as the focal point of this round; MSC and others plan to raise US East Coast FAK spot reference rates by USD 400-500/FEU in early September, pushing quotes above USD 10,000. Whether the September increase actually lands, however, will depend on booking demand and vessel utilization at the end of August.
The two routes appear to have different drivers — the Middle East route sees capacity squeezed directly by geopolitical conflict, while the US East Coast route is affected by canal restrictions combined with carrier capacity management — but in essence both point to the same core: global effective container capacity is being persistently drained by multiple factors.
Two critical international shipping chokepoints are under simultaneous pressure. The Suez Canal route continues to detour around the Cape of Good Hope due to Red Sea tensions, extending voyage times and reducing vessel turnaround efficiency; the Panama Canal is restricting transits due to drought, making queues and reduced loads the norm. On top of this, low water levels on multiple European rivers, port strikes in Germany, and typhoons disrupting Asian ports have further compressed already tight effective capacity, while strengthening carriers' confidence in raising surcharges and holding rates high.
For shippers, the simultaneous surge on both routes means cost pressure is spreading from a single market into a broad-based shock. With Middle East rates above USD 10,000, exporters to the region face the risk of freight costs exceeding cargo value; with the US East Coast approaching five figures and another GRI round expected in September, both importers and exporters are forced to weigh "locking in rates" against "waiting and watching." Market observers advise keeping a close eye on the implementation of the Strait of Hormuz temporary transit plan and the effect of Panama Canal restrictions in September, and securing space and rates in advance to avoid being forced to ship at unfavorable windows during the high-rate phase.
Disclaimer: The data in this article comes from public sources and is for industry analysis reference only. It does not constitute any decision-making advice. Actual freight rates are subject to carriers' official quotations.
联系人: Manager Li
电话: 021-31056166
邮件: sea-giant@sea-giant.com
地址: Room 1708, Pu Chuang Business Building, 1050 East Daming Road, Hongkou District, Shanghai, China